

PayMe - Claim Your Money analysis by Appwee
PayMe - Claim Your Money is a finance app from Prove It that focuses on a task many people postpone: checking whether they may be entitled to money from company settlements. I found the idea appealing because it turns a vague “I might qualify” thought into a more organized process. Instead of searching the web repeatedly and trying to remember which cases caught my attention, I can use one place to review opportunities and decide whether a claim is worth my time.
The app is free to install and is rated for Everyone, which makes it approachable for a broad audience. It has reached over 500 thousand installs and holds a 4.5 average from around 17 thousand ratings, so it is not an obscure experiment with no visible user base. Still, those figures should not be mistaken for a guarantee that every user will receive money. The central value is helping people find and pursue possible claims; eligibility and payment depend on the individual settlement and its rules.
How the everyday claim workflow feels
My recommended starting point is simple: open the app with a specific purpose rather than expecting an automatic windfall. I would browse the available settlement opportunities, read the basic explanation carefully, and then compare the stated eligibility conditions with my own history. That last step matters. A familiar company name does not automatically mean I qualify, and a claim is only useful when my experience matches the relevant requirements.
The strongest part of this baseline workflow is the reduction of scattered research. Settlement notices can be easy to overlook, especially when they arrive among ordinary emails or appear in news that I do not follow closely. PayMe gives the process a finance-oriented home, making it easier to treat potential claims as something to review deliberately instead of something I might remember months later.
I would keep supporting information nearby while checking a case. Depending on the settlement, that might mean dates, account details, purchase records, messages, or another indication that I used a product or service. I would not assume that a screenshot or receipt is always required, but I would avoid making a claim based only on a vague memory. A careful review at the beginning is faster than submitting something hastily and later discovering that the details do not line up.
One useful habit is to separate “interesting” from “actionable.” Some listings may look relevant because the company is familiar, while the actual eligibility window or affected product is narrower than expected. I would first save my attention for cases where I can clearly answer three questions: what conduct or product is involved, when it happened, and what evidence I can reasonably provide. That approach makes the app less like a lottery and more like a personal screening tool.
The developer, Prove It, has positioned the app around helping users claim money from settlements involving companies that allegedly harmed consumers. That wording describes the purpose without promising a result. In my experience, that distinction is important: the app can make discovery and organization easier, but it cannot replace reading the official terms or guarantee acceptance.
What I would check before submitting anything
Before moving through a claim, I would read the eligibility language slowly, especially the dates and definitions. Settlement wording often distinguishes between being a customer, buying a particular item, using a service in a certain way, or experiencing a specific problem. A quick tap through a form may feel efficient, but it can lead to an inaccurate submission.
I would also look at the deadline as soon as a case becomes relevant. A claim that seems perfect is not useful if I leave it until the last evening. PayMe is most valuable when it becomes part of a repeatable review routine: check new opportunities, investigate the ones that match my history, and complete the strongest candidates while I still have time to gather details.
Another practical point is to distinguish a possible payment from a guaranteed payment. Settlement distributions can depend on the number of valid claims, the available fund, and the administrator’s review. The app’s role is to help me find and pursue an opportunity, not to turn an uncertain legal distribution into a fixed income source. I would never plan a bill payment around a claim that has not been approved.
Settings and habits that make the app easier to manage
When I install a finance app, I do not rush past its setup screens. I look for notification controls, account preferences, and any options that affect how often I am interrupted. For PayMe, that matters because settlement opportunities are time-sensitive, but constant alerts can become noise. I would keep useful reminders enabled if available while avoiding a notification routine that makes me dismiss everything automatically.
I also recommend reviewing the app after installation rather than assuming the first configuration is ideal. The current version is 4.7, and the app supports Android 7.0 or later. That broad compatibility is convenient for people using older Android devices, although I would still keep the operating system and the app updated when possible. Updates can improve stability and reduce avoidable friction, even though an update should never be treated as proof that a particular claim is valid.
Privacy deserves a deliberate check. A claim may require personal information because the administrator needs to identify the claimant or verify eligibility. I would read each request in context and provide only what the process genuinely asks for. I would also be cautious about entering sensitive details into any screen that does not clearly relate to the settlement. The convenience of centralizing claims should not remove ordinary financial judgment.
Because the app is free to download but includes in-app purchases ranging from around five dollars to around three hundred dollars per item, I would pay attention to any purchase screen before confirming it. A user should understand what a paid option does, whether it is necessary for the claim being considered, and whether continuing without it is possible. I would never assume that paying improves eligibility or guarantees a larger settlement.
This is one of the most important trade-offs in the app. The free entry point makes it easy to explore, but the presence of optional purchases means I would use the same caution I apply to any finance service. If a claim appears small, uncertain, or difficult to verify, I would be especially reluctant to spend money simply because a paid feature is presented during the process.
A repeatable review routine
Experienced users will get more from PayMe by creating a small routine outside the app. I would set aside a short weekly check, keep a note of companies and services I have used, and record approximate time periods when those experiences occurred. I would not copy sensitive information into an unsecured note, but a simple private reminder can make later eligibility checks much quicker.
This habit solves a problem that the app alone cannot solve: memory. If I wait until a settlement appears before trying to remember every purchase or account, I may miss useful details. A lightweight personal record gives me a better starting point and reduces the temptation to guess. It also helps me dismiss irrelevant cases quickly instead of spending equal time on every listing.
I would create a short decision rule for myself: investigate when the company, product, time period, and alleged issue all match; pause when one of those pieces is unclear; and skip when the connection is only based on recognition. That rule makes the app faster without encouraging careless claims. It is a small but meaningful improvement over browsing without a plan.
Faster patterns for people who use it regularly
The quickest workflow is not to submit every possible claim immediately. I would first scan for relevance, then open only the opportunities that pass my initial check. This two-stage approach keeps the app from becoming a time sink. It also makes it easier to notice the details that matter, such as whether the case covers a particular product, region, or period.
When a claim does fit, I would complete it in one focused session if I have the necessary information. Switching between the app, old emails, bank records, and other documents can introduce mistakes. A better pattern is to gather the likely evidence first, then enter the information carefully. If I cannot finish, I would note exactly what remains rather than reopening the claim later with no plan.
Another useful pattern is to treat confirmation screens and messages as records. I would save the relevant confirmation in a secure place and note the settlement name and submission date. That does not change the decision, but it gives me a clear trail if I later need to remember what I submitted. I would avoid making duplicate claims simply because I have forgotten whether the first one went through.
PayMe can also be useful for people who help family members organize consumer matters, but I would keep each person’s information separate. Combining several people’s details in one hurried session creates unnecessary confusion. The person who may receive the payment should review the eligibility answers and understand what is being submitted. Convenience is not a reason to remove the claimant from the process.
For users who already monitor consumer settlements through email newsletters, legal websites, or news alerts, the app works best as a second layer rather than a total replacement. Those sources may explain the background in more depth, while PayMe can provide a practical place to identify and act on relevant opportunities. I would compare important details instead of assuming that one summary tells the whole story.
Where it beats ordinary alternatives
The usual alternative is doing everything manually: searching for settlements, opening administrator pages, checking deadlines, and trying to remember which cases were relevant. That method can offer more direct access to original documents, but it is easy to abandon because the process is fragmented. PayMe’s advantage is the focused consumer-claim workflow and the lower effort involved in finding possibilities in one finance app.
It is also more approachable than maintaining a spreadsheet of legal notices if the user simply wants a practical starting point. A spreadsheet can track deadlines and evidence very well, but it cannot discover opportunities by itself. PayMe is better for discovery and initial organization; a spreadsheet or private note may still be better for detailed personal tracking once several claims are in progress.
On the other hand, someone who wants extensive legal background, primary documents, or independent comparison may prefer going directly to official settlement sources. I would use those sources whenever the terms are complicated or the potential consequences are significant. The app is convenient, but convenience should not be confused with a complete substitute for reading the controlling information.
Advanced limits and situations where I would skip it
The biggest limitation is built into the subject itself: not every potential claim becomes a payment, and not every user will qualify. PayMe can reduce the effort of finding opportunities, but it cannot change the eligibility rules. A user expecting predictable returns will probably be disappointed. This is a tool for checking possible consumer compensation, not a conventional budgeting, banking, investing, or bill-payment app.
I would skip it if my goal were to track spending, build a budget, monitor investments, or transfer money. Those tasks require different tools and a different kind of financial information. The app’s narrow focus is a strength for settlement discovery, but it also means it should not be judged as a full personal-finance manager.
I would also be cautious if I disliked reviewing legal wording or keeping records. The app may make the first step easier, but responsible claiming still requires attention. If I am not willing to verify dates, products, and personal details, I would rather skip a questionable opportunity than submit an answer that is incomplete or inaccurate.
Paid options are another reason to set a personal boundary before using the app. Since individual purchases can reach around three hundred dollars, I would not approve one impulsively, particularly when the possible payment is uncertain. I would first ask whether the purchase is necessary, what practical task it performs, and whether the same claim can be completed through the ordinary free path or an official administrator channel.
There is also a difference between speed and quality. A fast interface can encourage users to tap through forms without understanding them. My advanced rule is to slow down at any question involving dates, purchases, account ownership, or the nature of the harm. Those answers are more important than shaving a minute off the process, and careful reading is the strongest protection against an avoidable error.
A realistic example of using it well
Imagine I remember using a company’s service during the period described by a settlement, but I am not sure whether my particular plan or purchase is included. I would open the opportunity, read the eligibility explanation, and search my own records for a matching date or transaction. If the details align, I would submit with accurate information and retain the confirmation. If the records show a different product or time period, I would stop there rather than stretching the facts.
That scenario shows both the app’s usefulness and its boundary. PayMe can bring a potentially relevant case to my attention and give me a clearer path forward. It cannot decide what happened in my account, interpret every ambiguous detail for me, or promise that a valid submission will produce a specific amount. The user still has to make the final judgment about accuracy.
My verdict after building a careful workflow
I see PayMe as a focused finance app for people who want a simpler way to look for consumer settlement opportunities. Its free starting point, Everyone age rating, and broad Android compatibility make it easy to try, while its 4.5 average and substantial install base suggest that many users find the concept useful. The experience is most convincing when I use it as an organized screening and submission aid rather than as a promise of easy money.
The smartest way to use PayMe is to combine its discovery workflow with your own careful records and judgment. Check relevant cases on a regular schedule, verify the details against your history, keep confirmations organized, and treat every paid option as a separate financial decision. Those habits make the app more useful without asking it to do something it cannot do.
I would recommend it to a consumer who often misses settlement notices, wants a central place to review possible claims, and is comfortable reading eligibility requirements before submitting. I would not recommend relying on it for ordinary money management, assuming every listing applies, or paying for an option without understanding its purpose. For the right user, it removes a frustrating amount of searching and remembering; for everyone else, official sources and a simple personal tracking system may be the better fit.
My final opinion is positive but measured. PayMe - Claim Your Money has a clear job, and it does that job best when I approach it patiently. It is not a shortcut around eligibility rules, and it is not a guaranteed payout service. Used as a repeatable habit—scan, verify, submit carefully, and keep records—it can turn overlooked settlement opportunities into claims I can evaluate with much more confidence.
Gallery
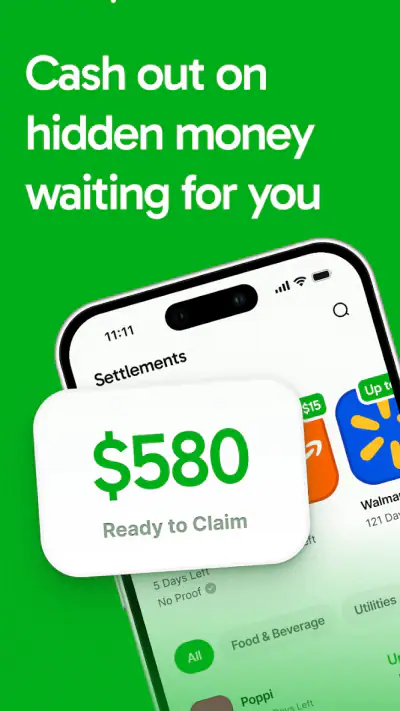
PayMe - Claim Your Money Pros and Cons
- Quickly sends payment requests to friends or contacts.
- Useful for splitting bills
- meals
- and shared expenses.
- Clear transaction history helps track requested payments.
- Supports convenient digital payments without handling cash.
- Simple interface makes occasional use easy for most users.
- Availability and features may vary by country or region.
- Both parties may need compatible accounts to complete payments.
- Payment processing times can depend on the selected method.
- Fees may apply for certain transfers or withdrawal options.
- Sharing payment details requires careful attention to privacy and security.
PayMe - Claim Your Money Frequently Asked Questions
What is PayMe - Claim Your Money, and how does it work?
PayMe - Claim Your Money is designed to help users discover and claim money or rewards that may be available through eligible offers, refunds, promotions, or other supported programs. After installing the app, you generally need to create an account, provide requested information, and follow the instructions shown for each claim. Availability and results can vary depending on your location and eligibility.
Is PayMe - Claim Your Money free to download and use?
The application may be free to download, but users should carefully review its terms before completing any claim. Some services can include processing charges, optional purchases, advertising, or conditions that affect how much money you actually receive. Before submitting personal or payment details, check the fee information, payout requirements, and cancellation rules displayed inside the app or on its official store listing.
What personal information does PayMe - Claim Your Money require?
Depending on the claim or payment method selected, PayMe may request details such as your name, email address, phone number, location, or payment information. Certain claims could also require identity or eligibility verification. Only provide information through the official application and review its privacy policy first. Avoid entering sensitive data if the request seems unrelated to the claim you are trying to complete.
How do I receive money or rewards through PayMe - Claim Your Money?
Payout options and processing times depend on the type of claim, your country, and the payment method supported by the app. You may need to reach a minimum balance, complete verification, finish an offer, or submit accurate account details before a withdrawal is approved. Always confirm the minimum payout, possible fees, and estimated waiting period before spending time on an offer.
Is PayMe - Claim Your Money safe and legitimate to use?
As with any app involving money, users should perform a few checks before relying on PayMe. Download it only from an official Google Play or Apple App Store listing, verify the developer name, read recent user reviews, and inspect the privacy and payment terms. Never pay unexpected fees to unlock a payout, and contact official support if a claim is delayed or an unusual request appears.














